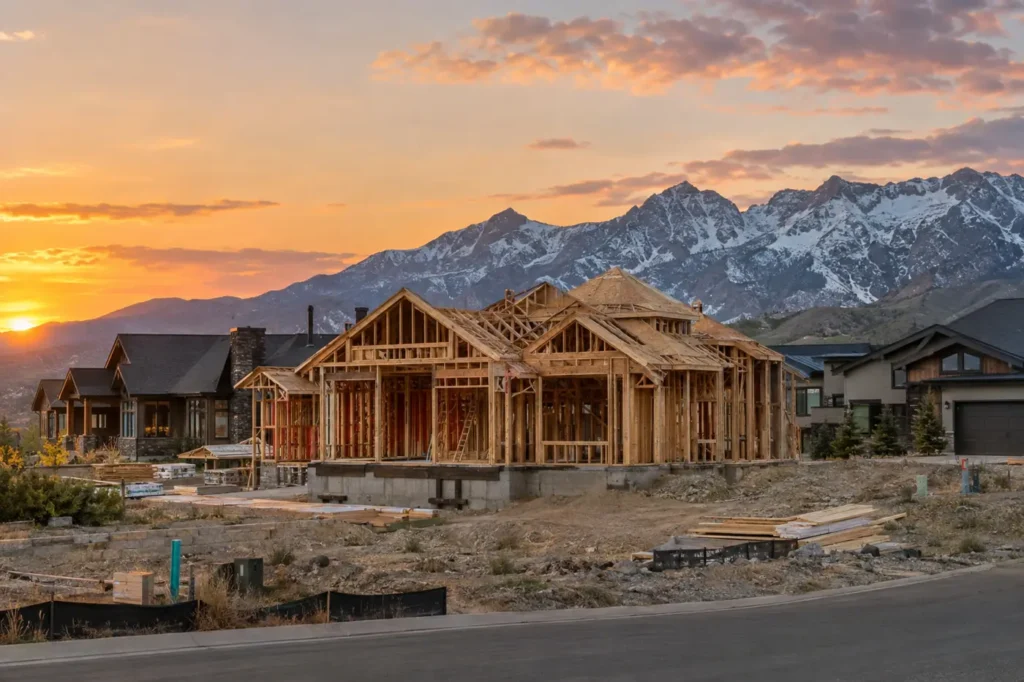
New Construction Incentives: What Is the Real Deal?
Builder incentives can be valuable, but compare the entire economic package: price, financing, upgrades, closing costs, appraisal, timeline and lender restrictions.
Builder incentives can be valuable, but compare the entire economic package: price, financing, upgrades, closing costs, appraisal, timeline and lender restrictions.
Paying points can lower a mortgage rate, but the decision depends on upfront cost, monthly savings and how long you keep the loan.
A lower monthly payment can still create a higher lifetime cost if fees, term reset or cash-out are ignored. Compare the full refinance structure.
The same seller concession budget can create very different buyer outcomes depending on whether it becomes a price cut, closing-cost credit or approved rate buydown.
The Federal Reserve is only part of the story. Mortgage rates reflect bond markets, lender pricing, borrower risk, loan structure and the property itself.
A mortgage-rate headline is a benchmark, not your loan quote. Compare the date, loan type, points, fees, borrower profile, and holding period before changing a housing decision.